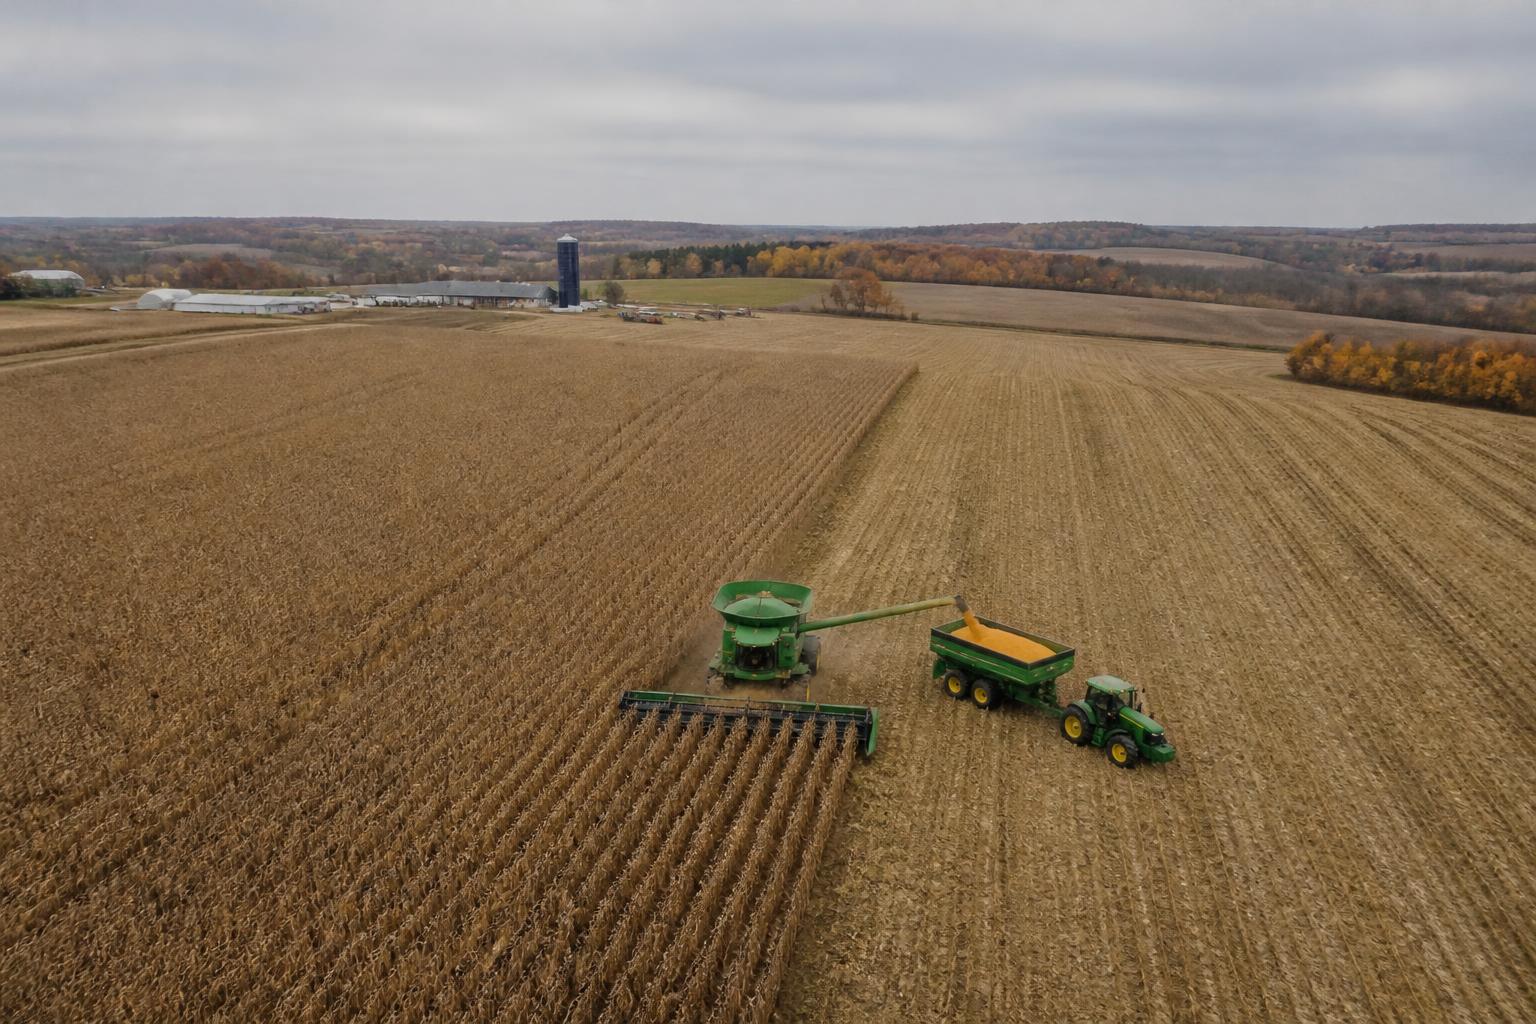
November has brought a series of rain events to Iowa, creating persistent challenges for producers looking to wrap up their final harvest activities. While operations in some regions, particularly across parts of Northwest Iowa, have neared completion, many growers are finding that current weather patterns are testing their patience and logistics as they push to finish the season.
As these field conditions persist, the focus for many is shifting from immediate harvest management to the broader market environment. The latest grain market insights remain critical as producers weigh their storage options against current price signals.
Market Sentiment and Federal Policy
Recent shifts in U.S. agricultural reporting have kept stakeholders on alert. Following adjustments to national corn output and soybean ending stocks, there is heightened discussion about how these supply figures might interact with global demand. Industry advocates continue to press for federal clarity, specifically regarding legislation for E15 and the broader farm bill, noting that stable policy is essential for long-term production planning and confidence.
Beyond domestic policy, growers are observing global market signals that could influence future export activity. Developments in trade relations remain a primary point of interest, as producers look for signs of increased demand for U.S. agricultural goods from key international markets.
Logistics and Equipment Trends
With the harvest season stretching into November, the pace of work has been notably impacted by moisture. Aside from immediate field issues, the industry is seeing a significant tightening in equipment supply. Recent data indicates a substantial year-over-year decline in dealer planter inventory, which may signal shifting capital investment strategies for the upcoming cycle.
What it means for the market
For Iowa agribusinesses and producers, the current environment is defined by a mix of weather-related delays and broader macro-economic uncertainty. Staying updated on regional yield performance and maintaining a flexible strategy regarding input and risk management will be paramount as we head toward the close of the year.
Comments
No comments yet - be the first to share your take.